Jio Platforms IPO | What you must know ...
As of this morning the Jio Platforms IPO is still days from opening. Nothing material has changed in the official terms since the Red Herring…
Research cut-off date: 17 October 2026.
As of this morning the Jio Platforms IPO is still days from opening. Nothing material has changed in the official terms since the Red Herring Prospectus was filed on 14 October. The public issue opens on 21 October and closes on 23 October. It is not yet open for subscription. Grey-market premium sits around ₹221–₹225 (roughly 20% over the upper band); treat that as unofficial sentiment only.
1. IPO Status
Jio Platforms has completed the formal steps. DRHP filed with SEBI on 19 June 2026. SEBI observation letter around 28 August. RHP filed with the Registrar of Companies, Gujarat, on 14 October and subsequently available on SEBI’s site.
The terms locked in the RHP are straightforward:
-
Entirely a fresh issue of up to 27 crore shares of ₹10 face value. No offer for sale. Every rupee raised stays inside the company.
-
Price band ₹1,065–₹1,119.
-
At the top of the band the company raises about ₹30,213 crore and the post-issue equity value sits near ₹10.3 lakh crore.
-
Pre-issue shares: 8,939,030,830. Dilution is only about 2.9%.
-
Anchor book on 19 October, public bidding 21–23 October, expected listing 28 October.
-
Up to ₹27,500 crore earmarked to prepay or repay borrowings of the material subsidiary Reliance Jio Infocomm. The rest goes to general corporate purposes.
-
RIL holds roughly 66.43% before the issue. Meta’s affiliate holds 9.98%, Google 7.73%. None of them are selling.
-
Reservations exist for eligible employees (up to ₹500 crore, ₹54 discount) and eligible RIL public shareholders (up to ₹2,500 crore).
Akash Ambani said on 15 October that the proceeds would help take the company toward net-debt-free status on the company’s own definition of net debt. The RHP also states the company has paid no dividends in the last three years and gives no assurance of future payouts; it may retain earnings for growth.
Earlier private valuations from 2020 (around $65 billion) are not equivalent to today’s equity value. Market conditions have already pulled the expected range down from higher numbers that circulated earlier this year.
From an IPO-readiness lens (the discipline Blue Mango emphasises for promoters preparing for public markets), this structure is clean on the primary-capital side. The harder questions for public investors are whether the systems, related-party economics, capital-allocation discipline, and leadership depth can sustain listed-company scrutiny once the merchant-banker checklist is done.
2. Why Should Investors Care?
Picture the company that carries more than 60% of India’s wireless data traffic, connects more than half a billion people, and is now telling investors it wants to turn that pipe into homes, enterprises and a technology stack it can sell abroad. That is the story Jio Platforms is bringing to the public market next week.
A listing of this size would be the largest IPO India has ever seen by rupee proceeds. It would also hand ordinary investors a direct claim on the infrastructure layer that most of the country’s digital life already runs on. For the Reliance group it is the moment the next generation of Ambanis steps fully into the spotlight with the business they have been building since 2016.
The question that actually matters is simpler than the headlines suggest. Are you buying a durable connectivity machine that still has room to raise what it earns from each customer and from each home, or are you paying a premium today for ambitions that have not yet shown up as material profit? Scale is real. Execution so far has been impressive. Whether that translates into attractive returns depends on the price you pay and on whether the next phase of growth arrives on schedule.
Big decisions deserve a second, qualified mind. In this case the “second opinion” is not whether Jio is large—it is—but whether the combination of ARPU trajectory, broadband unit economics, capital intensity, and related-party terms supports the multiple being asked.
3. Understand the Business
Jio Platforms is the holding company that sits above Reliance’s telecom and digital businesses. The engine is Reliance Jio Infocomm, the licensed operator that runs the networks.
Think of it as three layers. The first and largest is mobile connectivity—voice and data on 4G and 5G. That still produces the bulk of the revenue. The second is home broadband: fibre where it makes sense and fixed wireless (AirFiber and the company’s own unlicensed-band radio technology) where digging trenches is slow or expensive. The third layer is everything else—enterprise connectivity, the MyJio app and related services, and a growing set of technology and AI-related initiatives.
Not everything that carries the Jio name sits inside this company. Jio Financial Services was demerged and listed separately. Retail and energy live elsewhere in the group. Some services are delivered through related-party arrangements with other Reliance entities. The more ambitious pieces—large-scale AI services, satellite, or selling the technology stack overseas—are still mostly future opportunities rather than established, separately reported profit centres.
The company makes money the way any large telecom operator does: recurring monthly charges from a huge base of prepaid and postpaid customers, plus broadband subscriptions. Pricing power has been used in the past to win market share; more recently the industry has shown more discipline. High data consumption and low churn help. Enterprise and digital add-ons are higher-margin but still smaller. The business remains capital-intensive because networks, spectrum and expansion keep needing money.
Anyone who has run large telecom distribution and retention operations knows that the difference between a 50%+ EBITDA margin on paper and sustained free cash flow is often in channel productivity, billing migration discipline, churn control, and how cleanly related-party charges are managed. Those operational realities matter as much as the headline subscriber number.
4. Industry and Competitive Landscape
India’s telecom market has settled into an oligopoly. Three private operators matter; the rest are marginal. Jio is the scale leader on subscribers and on data traffic. Airtel is the closer rival on how much it earns per customer and on overall profitability. Vodafone Idea is constrained by its balance sheet.
As of mid-2026 the numbers look like this. Jio had about 524 million customers at the end of March and 533 million by the end of June, of which roughly 285 million were on 5G. Wireless market share sits near 39–40%. It carries more than 60% of the country’s wireless data traffic. Average monthly data use on its network has reached 43.7 GB. ARPU was ₹214 at the end of FY26 and ₹215.6 in the June quarter. Airtel’s ARPU has been running higher, in the ₹250–264 range in recent periods.
On fixed broadband Jio reported 28.6 million customers in June and took about two-thirds of the industry’s net additions in FY26. Management has called home broadband the biggest growth engine and has talked about expanding the addressable homes significantly, using a mix of fibre and wireless.
5G is largely built. The network covers nearly the entire population; utilisation still has room. Capital intensity, spectrum payments and regulation remain structural features of the industry. OTT services and global technology platforms are competitive pressures on some parts of the business, but the core connectivity layer still has high barriers.
A pure telecom operator is usually valued on cash flow and EV/EBITDA because the business is capital-heavy and partly regulated. A digital platform can justify a higher multiple if it shows software-like margins and network effects. Jio sits between the two. The cleanest Indian comparison is Airtel, particularly its India operations.
International Comparative Note
For international context, the most useful historical parallel is *China Mobile (listed in Hong Kong and New York in 1997 as China Telecom). It was the first major Chinese telecom privatisation, raised roughly US$4.2 billion at an IPO price of HK$11.80, and listed during the Asian Financial Crisis. The stock initially dipped with the market then recovered and closed the year above the issue price. Over the following decades it became the world’s largest mobile operator by subscribers and one of the largest telecom companies by market capitalisation. Today it trades at low single-digit EV/EBITDA multiples (around 4x) and high dividend yields, reflecting a mature, high-cash-flow but slower-growth business in a more saturated market.
Closer contemporary peers are T-Mobile US (growth-oriented US wireless player) and the large US incumbents Verizon and AT&T. T-Mobile has generally commanded a higher multiple than its US peers because of stronger growth and network leadership. Globally, pure-play telecom operators typically trade in the 6–9x EV/EBITDA range (Verizon and AT&T around 7x, T-Mobile around 9–10.5x, China Mobile around 4x). Indian operators have traded at a premium to these levels because investors price in faster ARPU growth, broadband expansion, and the benefits of industry consolidation in a still-growing digital economy.
Jio Platforms is being offered at an implied forward EV/EBITDA that sits above traditional global telecom multiples but is closer to (or modestly above) Airtel India’s India business. The comparison that matters most for long-term returns is not the 1997 China Mobile IPO price itself, but whether Jio can sustain growth and cash conversion closer to a high-growth emerging-market operator or whether it gradually converges toward the lower multiples typical of mature global telecoms.
5. Financial Deep Dive
These are consolidated figures for Jio Platforms drawn from consistent reporting of the company’s filings (₹ crore):
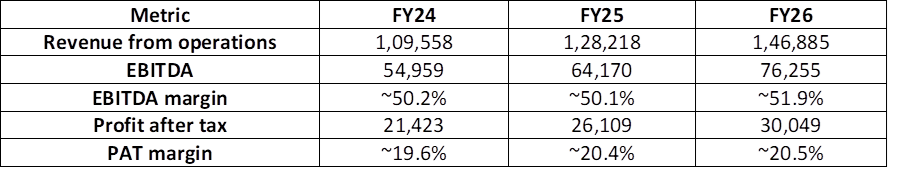
Revenue grew at roughly a 16% compound rate over the two years; EBITDA grew a little faster. In the June 2026 quarter revenue was about ₹39,173 crore (up 12% year-on-year), EBITDA about ₹20,865 crore (margin around 53%), and profit after tax about ₹7,764 crore.
The operating story underneath is straightforward: more customers, modestly higher ARPU, and rising data use. Cash generation improved sharply once the heaviest 5G spending eased. Net leverage fell from 0.88 times in FY24 to 0.36 times in FY26. Net debt was reported around ₹27,579 crore at the end of March 2026 and lower by June.
Two important caveats. First, the deferred spectrum liabilities owed to the government are large—around ₹1.04–1.05 lakh crore—and are not fully captured in the “net debt” number most people quote. Second, related-party transactions with other Reliance companies are material. The full picture of free cash flow, capital expenditure and the exact treatment of spectrum and leases sits in the offer documents. Summarised public data is good enough for direction but not for precise modelling.
A practical second-opinion check on these numbers asks: after spectrum and related-party adjustments, how much free cash flow remains once maintenance and growth capital are paid? High reported margins are necessary but not sufficient.
6. Growth Engines: What Could Drive the Next Phase?
The existing engine is still working: keep adding customers, keep them using more data, and let industry pricing discipline lift ARPU over time. The company is pointing to several additional levers.
Management has been clear that it prefers to grow revenue by selling more services rather than simply raising the price per gigabyte, though it keeps the option of tariff increases. Telecom spending as a share of per-capita income has fallen since 2016, which they see as headroom. 5G is already widely used; the question is how much extra customers will pay for better experience or for enterprise uses. Home broadband is the area they have highlighted most loudly. They have talked about expanding the homes they can reach toward 100 million, using both fibre and their wireless technology, and noted that a large share of recent additions is coming from smaller cities. Enterprise digital services and the idea of licensing or managing their technology stack for operators abroad are longer-term possibilities. AI and cloud partnerships exist, but they have not yet shown up as material, separately reported profit.
A large addressable market is not the same as profitable revenue. Each of these opportunities needs capital, execution and a competitive response that does not erase the returns. The nearest-term improvements are more likely to come from ARPU discipline, broadband scale-up and the natural operating leverage that appears once peak network spending slows.
From an operating perspective, broadband growth will ultimately be judged by unit economics, channel productivity, and whether fixed-wireless additions in smaller cities sustain ARPU and low churn—not by the total homes addressable.
7. Management, Governance and Ownership
Mukesh Ambani remains Chairman in a non-executive role. Akash Ambani is Managing Director and has been the public face of the IPO process. Isha and Anant Ambani sit on the board. Pankaj Pawar is CEO. The 2026 AGM commentary indicated that the transfer of day-to-day responsibility to the next generation is well advanced. The track record of building the network and the 5G footprint is strong.
RIL will still own a clear majority after the listing. The strategic investors who came in during 2020 are staying put. Related-party arrangements with the rest of the group are extensive and have been approved by RIL shareholders for multi-year periods. Standard SEBI minority protections apply, but the concentration of control and the volume of intra-group business are structural features, not temporary ones. No unique governance scandals have been highlighted in credible coverage. The dividend policy makes clear that returns for public shareholders will depend primarily on the share price, not on payouts.
IPO readiness frameworks typically weight governance & compliance, leadership depth, and systems & processes heavily. Here the track record of execution is strong; the open questions for minority investors are the durability of related-party terms and the depth of independent oversight once listed.
8. Valuation: What Might Jio Platforms Be Worth?
At ₹1,119 the post-issue equity value is about ₹10.3 lakh crore. On FY26 profit after tax of roughly ₹30,049 crore that is a trailing multiple of about 34 times. Adjusting for net debt and the large spectrum liabilities, various analysts have placed the implied enterprise value around 10.5–11 times forward EBITDA—generally a modest premium to estimates for Airtel’s India business.
How global investors typically value telecoms versus Jio Platforms
Global pure-play telecom operators are usually valued on EV/EBITDA and free-cash-flow yield because the businesses are capital-intensive, partly regulated, and mature. Typical ranges in 2026 sit roughly as follows:
-
Mature US and European operators (Verizon, AT&T, Deutsche Telekom): often 6–8x EV/EBITDA, with higher dividend yields.
-
Higher-growth or network-leadership names (T-Mobile US): closer to 9–11x.
-
Large Asian mature operators (China Mobile): often 3.5–5x, reflecting slower growth and high cash returns via dividends.
-
Emerging-market growth stories and Indian operators: higher multiples that price in ARPU expansion and broadband scale-up.
Jio is being offered at a multiple that sits above most global pure-play telecoms and modestly above Airtel India’s India business. The premium is justified by investors only if ARPU keeps rising, broadband scales profitably, capital intensity moderates, and the company continues to convert scale into free cash flow. If growth slows toward mature-market rates, the multiple would be expected to compress toward global norms over time.
Three illustrative scenarios, using FY26 actuals and peer context as of mid-October 2026:
-
Conservative: slower ARPU growth or heavier ongoing capital spending, and a multiple closer to traditional telecom peers (say 8–9.5 times forward EV/EBITDA). That would put equity value meaningfully below the upper end of the band.
-
Base case: growth in the low-to-mid teens on EBITDA and a multiple in the 10–11 times range, roughly in line with or slightly above Airtel India. That is consistent with the upper end of the current price band looking reasonable if the company continues to convert scale into cash.
-
Optimistic: broadband and enterprise contribute faster, industry pricing stays disciplined, and the market is willing to pay 12–13 times or more. Equity value would sit above the upper band.
Airtel’s overall market capitalisation is in the ₹11.5–12 lakh crore area, but that includes Africa and other holdings; its pure India wireless business is usually valued lower on a like-for-like basis. Global pure-play telecom operators typically trade at lower multiples. The 2020 private valuation is not a useful anchor for today’s public equity value. The limitations are real: spectrum and lease adjustments are not fully transparent in summary data, related-party economics can affect margins, and the digital/AI upside is still mostly prospective. The modest dilution from the fresh issue does not change the overall picture much.
9. IPO Structure and Use of Proceeds
The structure is clean on paper: 100% primary, small dilution, proceeds used mainly to reduce bank debt at the operating subsidiary. That should improve interest coverage and free-cash-flow conversion, moving the company closer to net-debt-free status on its reported definition. Large deferred spectrum liabilities remain. Employee and RIL-shareholder reservations are in place. Anchor demand and final subscription numbers will only be known once the book opens. Lock-ins follow the usual SEBI rules. The RHP is the document that contains the full risk factors and the detailed use-of-proceeds tracking.
Before applying, investors should be clear on the post-issue net debt after spectrum and lease adjustments, the commercial terms of related-party arrangements, the capital-expenditure outlook, and the specific targets management has for ARPU, broadband and non-telecom contribution.
10. Key Risks and Red Flags
In rough order of impact:
-
Paying a multiple that assumes growth arrives on schedule. Watch actual ARPU, margins and free cash flow against the expectations embedded in the price.
-
Slower ARPU progress or a return to price competition. The gap to Airtel’s ARPU is still material.
-
Capital intensity that does not moderate as expected. Broadband and any technology ambitions still require spending.
-
Regulatory and spectrum risks. The deferred payment schedule is large and long-dated.
-
Residual debt and cash-flow pressure once spectrum liabilities are properly included.
-
Dependence on the broader Reliance group and the volume of related-party transactions.
-
Execution risk on AI, cloud, technology export and other newer businesses.
-
Ordinary promoter-control and disclosure risks. The absence of a dividend history means returns rest entirely on capital appreciation.
None of these are unique red flags that have not been discussed. They are the normal risks of a large, capital-intensive, promoter-controlled infrastructure business that is also asking to be valued partly on future optionality. The practical filter is whether the business can keep converting scale into cash after the listing excitement fades—the same discipline that separates a successful listed company from one that merely listed.
11. Investment Verdict
-
Is Jio Platforms potentially a high-quality business? Yes. It has durable scale, network leadership, improving profitability and a large base of recurring revenue in an industry that has consolidated.
-
Strongest advantages: subscriber and data-traffic leadership, the 5G footprint, the ability to bundle home broadband, a proprietary technology stack, and access to group distribution and capital.
-
What could stop those advantages from becoming good shareholder returns? Paying too much today, slower monetisation of ARPU or broadband, persistent high capital spending, regulatory setbacks, or related-party terms that do not fully favour minority holders. With no history of dividends, the return case is almost entirely about the share price.
-
Valuation assumptions: at or below the upper end of the band the case looks reasonable for long-term holders who believe industry discipline and broadband growth will continue. Materially higher would look expensive without clear acceleration. Lower would be more attractive.
-
Investor profiles: long-term investors who want exposure to India’s digital infrastructure and are comfortable with promoter control may find it relevant. Investors who prioritise free-cash-flow yield, higher returns on capital, or simpler corporate structures should be more cautious. Short-term trading around the IPO carries the usual volatility and grey-market noise.
-
What still needs to be seen: actual subscription and allotment data, the first few quarters of post-listing results, and ongoing evidence on the risks listed above. The full RHP is the primary document.
The One Thing Investors Must Remember
You are buying the dominant Indian connectivity business, with real optionality on homes and technology, at a price that already assumes a fair amount of that optionality will pay off. The listing makes the value visible. The returns will depend on whether ARPU, broadband and cash conversion keep compounding faster than the multiple compresses. Strategy without execution is hallucination; execution without disciplined capital allocation is chaos.
Disclaimer
This article is for informational and educational purposes only. It is not investment advice, a recommendation to buy or sell any securities, or an offer to invest. It is based on publicly available information as of 17 October 2026 and may contain errors, omissions, or outdated data. IPO pricing, subscription levels, listing performance, and future financial results are uncertain. Grey-market premiums are unofficial and unregulated. Investors should conduct their own independent research, read the full Red Herring Prospectus and related offer documents, and consult a qualified financial advisor before making any investment decision. Past performance of comparable companies is not indicative of future results. The authors and publishers accept no liability for any loss arising from the use of this information. Perspectives drawn from Blue Mango Consulting Group’s public positioning and frameworks are for contextual illustration only and do not constitute an endorsement or advice from the firm.